Additionally, several crucial individuals, including an indianapolis title company, facilitate a seamless property sale or purchase behind the scenes.
How Real Estate Brokerage Leading The Way
Most homebuyers and sellers start at a real estate brokerage. It uses real estate agents to represent buyers and sellers.
They enter the process:
For Purchasers
For Sellers
Financing Through Mortgage Brokers
A mortgage brokerage, including an indianapolis title company, connects borrowers and lenders. Moreover, it helps purchasers get house loans.
Details about their transaction role:
The Title Company's Obligations To Maintain Clear Ownership
A title business ensures that the property title is clear of liens and encumbrances and that ownership is transferred legally.
Obligations include:
Additionally, an indianapolis title company conducts the title search.
The title firm exhaustively searches public documents to verify the property's ownership history and locate any liens or easements.
2. Title Insurance
They insure the buyer and lender against ownership issues.
3. Escrow Services
The title business holds monies and papers until all selling conditions are met.
4. Preparing Legal Documents
They create and analyze closing documents to ensure legal compliance.
5. Facilitating Closing
At closing, the title company signs all documents, disburses monies, and registers the transaction with the government.
How Do Real Estate Brokerage, Mortgage Brokerage And Title Company Cooperate?
1. Communication
Effective communication between real estate agents, mortgage brokers, and title companies is crucial. To achieve a smooth process, parties must communicate and collaborate.
2. Problem-Solving
Teamwork solves problems like low appraisals and title defects. The mortgage broker alters loan terms, the title firm addresses title concerns, and the real estate agent negotiates repairs or price modifications.
3. Closing Prep
Each party checks conditions as closing approaches. The mortgage broker approves loans, the real estate agent finishes inspections, and the title business prepares closing documents.
4. The Final Steps
On closing day, the buyer, seller, agents, and mortgage broker meet at the title firm. The title business verifies paperwork, distributes payments, and registers deeds.
What Are The Importance Of Each Role?
1. Real Estate Brokerage
Their negotiation and local market experience are invaluable. They help buyers find quality homes, and sellers obtain the greatest price.
2. Mortgage brokerage
Finding the most suitable loan packages and costs saves buyers time and money. Their knowledge simplifies mortgages.
3. Title Company
The title company ensures the property's title is valid, and the transaction is legal. Title insurance prevents future claims.
Conclusion
Buying and selling a home relies on real estate, mortgage, and title companies. Each entity has a unique but interrelated function in ensuring legal, seamless, and financially sound transactions. Buyers and sellers can confidently negotiate real estate by knowing how these parties work together.
Your experience as a property owner begins when you close on a new house. New tasks and obligations await in this new chapter. Building relationships with your new neighbors is an important part of homeownership; however, things such as encroachment can cause conflict. And these conflicts may cause bigger problems over time when not resolved.
In this post, we'll learn what encroachment is in real estate and how to resolve disputes quickly so you can enjoy your home.
Encroachment in real estate is when a property owner infringes on their neighbor's property rights. Constructing or expanding a feature that crosses the property line onto the neighbor's land is a common example. It can also happen underground; for instance, installing utilities below the ground.
For instance, a lemon tree limb may have grown to the point where it extends into the neighbor's yard. Alternatively, a shed or fence that spans property lines has been constructed.
Property invasion is frequently an accident; it may occasionally be deliberate. In certain instances, the previous homeowner completed it. An ambiguous property boundary could be the cause. Actually, until a survey shows the encroachment, many property owners are unaware of it.
Property boundary disputes can arise in several ways. Let's examine a few typical forms of real estate encroachments.
Minor Encroachments
A minor encroachment is either short or insignificant. It has no lasting effect, can be quickly and easily fixed, and is usually resolved with informal discussions or negotiations.
A garden bed that extends just a little bit into a neighbor's yard or a tree branch that hangs over their side of the fence are some examples of minor encroachments. It can also involve a little landscaping and movable things like basketball hoops and trash cans.
Structural Encroachments
Building construction that crosses the property border might be considered a structural encroachment. It may also be a more significant, larger, or long-lasting obtrusion. Nonetheless, it has a greater impact and may cause long-term issues. Generally speaking, a structural encroachment is viewed as a major encroachment, and moving or changing it could be more difficult and costly, or legal action might be required.
For example, it could mean permanent landscaping, utility installations, adding fences, garages, or balconies, or expanding a portion of one's house are a few examples.
Major Encroachments
Significant real estate encroachments may impact the owner's property rights and enjoyment of their land. The home's value may potentially be impacted. Major encroachments are typically seen in several structural encroachments.
Major and structural encroachments are more costly and difficult to fix. They may thereby increase the likelihood of legal problems and court disputes. Major encroachments include things like building expansion beyond property lines or subterranean utility installation on your neighbor's land.
A neighbor encroaching on your property can place you in an awkward position, leading to problems. That said, it's a good idea to seek help from a professional land surveyor if you suspect a neighbor infringing on your property.
Land surveyors are experts in measuring and charting a land's surface. Legal property borders can be established using a competent land survey. In this manner, you can determine the location of the property line.
The average cost of a land survey is $2,300. According to Angi's data, most households may spend between $475 and $25,000, depending on factors like the size, topography, location, and topographical.
Asking your neighbor if they're willing to divide the price since it's expensive might be a good idea. After all, it will give you both clarity and help you avoid future problems.
The good news is that the majority of encroachments are usually quite small and may be fixed without incurring additional costs or difficulties. For instance, trimming a bush that has spread into the backyard of a neighbor.
However, significant encroachments can result in some major and expensive issues.
Encroachments may result in the following problems:
An easement is a legal right that permits one person or organization to utilize another's real estate for a particular purpose, like utility maintenance or access to a landlocked tract. For instance, rights-of-way, shared driveways, power and water lines, and other utilities.
Both parties agree on easements. Even if they are still accepted, easements can nevertheless lead to certain problems, like:
If you come across a property invasion, following the right procedures can help you determine what to do to prevent things from getting worse:
Acquire A Land Survey
Working with a professional land surveyor to confirm the property lines if you think your neighbor may be infringing on your property is advisable.
Negotiate With Your Neighbor
It might sound daunting, but talking about your issue with your neighbor, even something as small as an overhanging tree branch, helps in resolving encroachment.
They are likely unaware of the problem. You can save a lot of time and worry and maintain good neighbor relations if you can resolve conflicts with your neighbor immediately.
Give An Easement To Your Neighbor
Give your neighbors an easement if it makes sense to do so. In this manner, it provides them with access to the impacted area of the land. This may be a win-win scenario.
You should work out particular arrangements with your neighbor if you're considering taking this approach. For instance, specify the precise portion of the land they can visit, any compensation, and what is and is not allowed. This can stop new problems from emerging.
A documented easement deed that is signed by both parties is required to legitimize an easement. They are typically registered with the deeds to each neighbor's property and must be filed with the county clerk's office.
Sell Your Neighbor The Land
Redrawing the property line and selling the land entirely are alternatives to giving an easement. In this manner, you are paid for the neighbor's use of the land, and they can access it without fear of legal consequences.
Take Legal Action
It might be time to take legal action if your neighbor refuses to remove the encroachment and you're unable to reach a deal on a land easement or sale. Find a reputable lawyer who has experience with boundary disputes to help with this.
FAQs On Encroachment
Is it illegal to encroach?
Encroachment is not a criminal offense but rather a civil one. However, if, for example, the neighbor refuses to remove it and trespasses on your property, it may result in criminal charges.
Should I purchase a home that has an encroachment?
It depends. What you have to remember is that even a minor encroachment might mean that your neighbor won't be considerate of the property line and your space. So, before buying a home with encroachment, you must weigh its pros and cons, as it can affect your home's title and value.
Can you relocate your neighbor's land away from your own?
Before removing an encroachment, have a straight conversation with your neighbors. Regretfully, relocating items that aren't yours could result in escalating conflict with your neighbor and a number of legal problems, even if they are on your land.
Is it possible for my neighbor to build all the way to the edge?
The local zoning law and construction standards determine whether a neighbor may build all the way to the boundary. Regarding trees, you should review the tree law, which outlines each party's rights regarding trees on or close to their land.
Can a house with an encroachment be sold?
Yes, a home with an encroachment can still be sold. However, it can have an impact on buyer interest, appraised worth, and buying price.
Conclusion
Encroachment may not pose a high risk; however, if you want to have good ties with your neighbors and defend your property rights, you must resolve the problem right away.
While major encroachments may require legal action, minor encroachments, such as landscaping that crosses property lines, can usually be handled with proper negotiation.
If you have questions on encroachment, feel free to leave them in the comments.
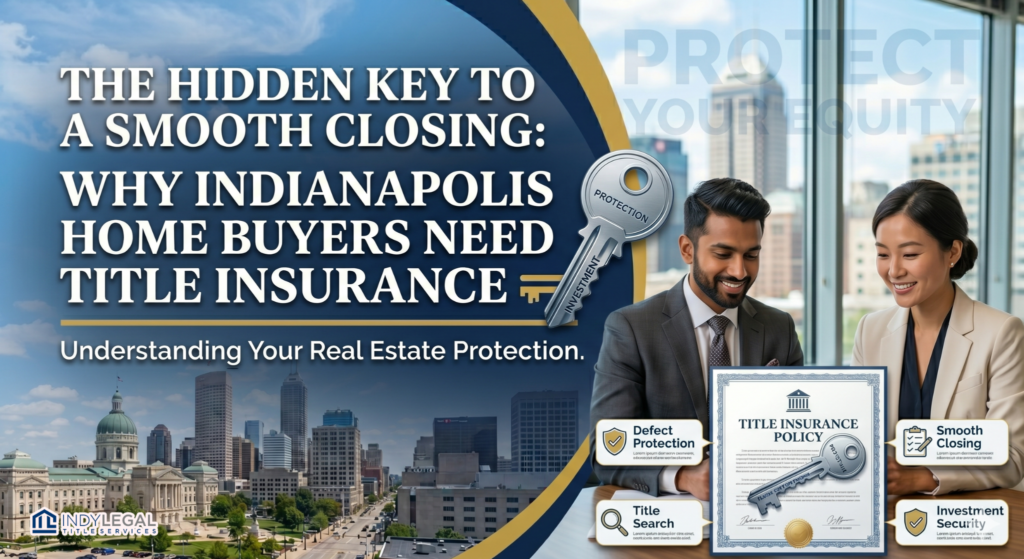
Buying a home is the ultimate Indianapolis dream. Whether you’re eyeing a historic craftsman in Meridian-Kessler, a modern townhome in Fountain Square, or a family retreat in Fishers, there is one crucial step that ensures the home you’re buying is actually yours to keep: Title Insurance.
As a local title company, we see the "behind-the-scenes" of every real estate transaction. Here is everything you need to know about why title insurance is your most important line of defense.
Unlike car or health insurance, which protects you from future accidents, title insurance protects you from past events.
Think of it as a comprehensive background check on your property. Our job is to dig through decades of public records in the Marion County Recorder’s office (and surrounding counties) to ensure there are no "clouds" on the title. These include unpaid debts, legal disputes, or ownership errors that could threaten your investment.
Even the most careful search can miss issues that aren’t in the public record yet. Here are three common scenarios we resolve for Indianapolis buyers:
In Indiana, you will likely see two types of policies on your closing disclosure:
| Policy Type | Who It Protects | Is It Required? |
| Lender’s Policy | The Bank or Mortgage Company | Yes (by the lender) |
| Owner’s Policy | You (The Homeowner) | Optional, but highly recommended |
Crucial Note: A Lender’s Policy only covers the amount of the mortgage and only protects the bank. To protect your down payment, your equity, and your right to live in the home, you need an Owner’s Policy.
In the Indianapolis area, who pays for the title insurance is often a point of negotiation in the Purchase Agreement.
While your lender might suggest a national provider, choosing a local Indianapolis title company offers several advantages:
Your home is likely your largest financial asset. For a one-time fee paid at closing, title insurance provides a lifetime of security. It ensures that when you finally turn the deadbolt on your new front door, you can rest easy knowing that your "Home Sweet Home" is legally, safely, and entirely yours.
Is your path to homeownership ready to be secured? For most people, a home is the largest investment they will ever make. Don't leave that investment to chance. Reach out to our expert Indy title team today to learn how we protect your interest from the moment your contract is signed all the way to a smooth closing day.
How Much Does Title Insurance Cost in Indiana?
A Comprehensive Guide for Hoosier Homebuyers and Sellers
Buying a home in Indiana is a major milestone, whether you are choosing a historic craftsman in Indianapolis, a quiet spread in Carmel, or a lakefront property in Northern Indiana. However, the closing process often brings a wave of paperwork and unexpected costs. Among these, title insurance is frequently misunderstood yet remains one of the most vital protections for your investment.
As your local title experts, we believe transparency is the foundation of a smooth closing. In this guide, we break down exactly what you can expect to pay, who is responsible for the bill, and how you can ensure you're getting the best value for your Indiana title policy.
1. The Basics: What Determines the Cost?
Unlike monthly homeowners insurance, title insurance is a one-time premium paid at closing. In Indiana, the cost is primarily determined by the purchase price of the home (or the loan amount for a lender's policy). Title companies in Indiana must file their rates with the Indiana Department of Insurance (IDOI). While rates are relatively competitive, they are tiered: as the property value increases, the rate per thousand dollars of value typically decreases, even as the total premium rises.
Estimated Premium Breakdowns (State Averages)
Home Purchase Price Est. Owner's Policy Premium
$150,000 $850 – $1,100
$300,000 $1,400 – $1,750
$500,000 $2,100 – $2,500
$1,000,000 $3,800 – $4,400
*Note: These figures are estimates. Actual rates vary based on the specific title agency
and any necessary county endorsements.’
2. Two Types of Policies: Who Pays?
In a standard Indiana real estate transaction, there are two separate policies involved. Local custom often dictates who pays for which, but this remains negotiable in your purchase agreement.
The Owner’s Policy
This protects the buyer from claims against the property (like unknown heirs or undisclosed liens). In many Indiana counties (including Marion and the surrounding areas), it is customary for the seller to pay for the Owner’s Policy as a way to provide the buyer with a "marketable title."
The Lender’s Policy
If you are financing your home, the bank will require a policy to protect their mortgage interest. The buyer (borrower) almost always pays for this.
The "Simultaneous Issue" Discount: When both policies are purchased at the same time through the same company, you qualify for a significant discount. The lender's policy is often reduced to a flat fee (typically $100 to $250), rather than a second full premium.
3. Additional Service Fees to Watch For
The "Premium" is the insurance component, but title agencies also perform the administrative heavy lifting required to close the deal. In Indiana, you should budget for the following service fees:
Search and Exam Fee ($200 - $400): The cost of expertly researching the chain of title in county records to ensure no surprises exist.
Settlement/Closing Fee ($350 - $600): The fee for the professional agent who coordinates the signing and manages the escrow of funds.
TIEFF Fee ($5): The Indiana Title Insurance Enforcement Fund Fee (a state- mandated fee).
Recording Fees: Charged by the County Recorder to officially update the deed and mortgage records.
4. How to Ensure the Best Value
At our company, we believe an educated consumer is our best partner. Here is how you can manage your title costs:
Know Your Right to Choose
In Indiana, you are not legally required to use the title company recommended by your lender or real estate agent. You have the right to select your own provider. We encourage you to compare "Good Faith Estimates" to ensure you are receiving competitive service fees and transparent communication.
Ask About the "Reissue Rate"
If the seller has owned the home for less than 10 years, you may be eligible for a "Reissue Rate." By providing a copy of the previous title policy, we can often apply a discount of 10% to 40%, as much of the foundational research was recently completed.
Conclusion
While title insurance might feel like just another closing cost, it is the only thing standing between you and potentially devastating legal claims. In Indiana, you can generally expect total title-related costs to hover around 0.5% to 1.0% of the home's value.
Experience a Seamless Closing
Our team is dedicated to providing Indiana homeowners with peace of mind through expert title research and transparent pricing. Have questions about your specific property? Contact us today for a detailed quote.
In the Indianapolis real estate market, the closing table is where a deal transforms from a spreadsheet calculation into a tangible asset. For investors, the process in Indiana has unique quirks. From "dry" vs. "wet" closing customs to new 2026 federal transparency requirements, these details can either protect your ROI or drain it through delays.
If you are scaling a portfolio in the Circle City, here is the essential guide to navigating title and closing in 2026.
As of March 1, 2026, the era of "all-cash, no-questions-asked" for entities has shifted. New federal regulations from the Financial Crimes Enforcement Network (FinCEN) now require title companies to file a Residential Real Estate Report for certain non-financed transactions involving LLCs, corporations, or trusts.
In many states, one title company handles every aspect of the transaction. In Indianapolis, "split closings" are common. This means the seller may choose one title company to clear the title, while the buyer or investor chooses another to handle the closing and the new title insurance policy.
In 2026, Indianapolis remains one of the most investor-friendly markets in the country, but you still need to budget for the silent costs. On average, seller closing costs in Indiana hover around 2.74%. As a buyer, your focus should be on the following:
Indianapolis is a hub for wholesaling and "Subject-To" deals. These require a title company that truly understands investor-specific maneuvers.
A critical update for 2026 is Indiana Senate Enrolled Act 256. This law restricts individuals and entities from "adversarial countries," including Russia and China, from purchasing or leasing real estate in Indiana.
In the 2026 Indianapolis market, the winning investor is not just the one who finds the best deal. It is the one who closes the most efficiently. With the market settling into a healthier balance, your ability to navigate the legalities of title and the new FinCEN transparency rules will give you a competitive edge.Pro-Tip: Always ask for a Preliminary Title Report within the first seven days of escrow. In Indy’s historic neighborhoods, old utility easements or decades-old mechanics' liens can pop up. Catching them early is the difference between a smooth flip and a legal nightmare.
Buying a home in the Circle City is a major milestone. Whether you are eyeing a historic cottage in Irvington or a new build in Noblesville, the excitement of the "find" often overshadows the technicalities of the "close." However, selecting a title company is one of the most critical decisions in the real estate process.
In Indiana, the title company acts as the neutral third party that ensures the seller has the legal right to sell the property and that no hidden liens or claims will haunt you later. Here is how to choose the best partner for your Indianapolis closing.
Many first-time buyers assume they must use the company recommended by their lender or real estate agent. While professional referrals are helpful, Indiana law allows you to shop around. Since title insurance is a one-time fee paid at closing, choosing a company with competitive rates and high service standards can save you both money and stress.
Indianapolis has unique property nuances. A title company with local expertise will be familiar with specific township taxes, local utility liens, and homeowner association (HOA) hurdles common in areas like Carmel or Fishers. Local firms often have established relationships with county recorders, which can lead to faster processing times.
Title costs in Indiana are not set by the state, so fees can vary. Request a "Title Quote" or "Good Faith Estimate" from at least two companies. When comparing, look at these specific items:
Wire fraud is a significant concern in modern real estate. A top-tier Indianapolis title company should prioritize digital security. Ask if they use secure portals for sharing wire instructions and if they offer encrypted communication. Furthermore, check if they provide modern conveniences like Remote Online Notarization (RON) or mobile notaries if you cannot make it to a physical office during business hours.
A company’s reputation among local professionals is a strong indicator of their reliability. Look for firms that maintain high ratings on Google or the Better Business Bureau. You want a team that is known for proactive communication. There is nothing worse than being "left in the dark" while waiting for your clear-to-close.
Always confirm that the agency and the individual title agents are properly licensed through the Indiana Department of Insurance. This ensures that the professionals handling your transaction are authorized by the state and held to the required regulatory standards.
Before making your final decision, call a few offices and ask these three questions:
The right title company provides more than just a stack of papers. They provide peace of mind that your investment is legally sound. By doing a little homework upfront, you can ensure that your Indianapolis home-buying journey ends with a smooth and celebratory closing.
Buying a home is likely the biggest investment you will ever make. You have checked the foundation, the roof, and the plumbing, but have you checked the history?
Before you sign on the dotted line, there is one invisible hurdle every buyer must clear: the Title Search. Here is everything you need to know about what it is and why skipping it is a risk you cannot afford to take.
A title search is a thorough examination of public records to confirm a property’s legal ownership and discover any "clouds" or claims against it. A title professional or attorney combs through documents that often date back decades. These include:
The goal is simple. The process ensures the person selling the home actually has the legal right to sell it and that you will own it "free and clear."
You might think a clean-looking house means a clean title, but legal issues are not always visible during a walkthrough. A title search protects you from these common pitfalls:
If the previous owner owed back taxes or had unpaid contractor bills, those debts stay with the property rather than the person. Without a title search, you could inherit someone else’s debt the moment you close.
Perhaps the seller’s long-lost sibling claims they inherited a 50% stake in the house ten years ago. It is also possible that a previous deed was forged. A title search identifies heirship issues or fraudulent filings that could contest your right to live there.
An easement might give a utility company the right to dig up your backyard or a neighbor the right to use your driveway. An encroachment happens when a structure, such as a fence or garage, is built over the property line. Knowing these limits ahead of time prevents legal battles with neighbors later.
Even the best title search might miss something deeply buried. Examples include a forged signature from 1950 or an undisclosed heir.
This is where Title Insurance comes in. It is a one-time fee paid at closing that protects you and your lender from financial loss due to title defects that were not discovered during the initial search.
A title search provides peace of mind. It transforms a "house for sale" into a "secure investment." By identifying potential legal headaches before you hand over your life savings, you ensure that your new home truly belongs to you and only you.
Buying or selling property in the Hoosier State involves more than just a handshake and a deed. In Indiana, the title company acts as the "referee" and the "engine" of the real estate transaction. At IndyLegal Title Services, we leverage over 50 years of experience to ensure that when a keys change hands, the ownership is ironclad.
Here is a step-by-step breakdown of our role from the moment we receive the purchase agreement to the final signature at the closing table.
1. The Title Search & Examination
Once a contract is signed, our work begins with a deep dive into Indiana’s public records. We don't just look at the current owner; we look at the history of the land.
2. Title Insurance Commitment
After the search, we issue a Title Commitment. This is a legal promise to issue an insurance policy provided certain requirements (like paying off the seller's mortgage) are met.
3. Escrow & Coordination
As an escrow agent, IndyLegal acts as a neutral third party. We hold the "earnest money" and coordinate with all parties: realtors, lenders, buyers, and sellers.
4. The Closing (Settlement Services)
This is "Signing Day." We facilitate the meeting where the legal transfer of the property occurs.
5. Post-Closing & Recording
Our job isn't done when you leave the table. We take the signed Deed and Mortgage to the County Recorder’s office (e.g., Marion, Hamilton, or Hendricks County) to officially record the change in ownership.
The Result: You walk away with peace of mind, knowing your investment is legally protected and your title is clear.
Frequently Asked Questions
Does Indiana require a title company for closing?
While not strictly required by state law, almost all lenders require title insurance to protect their investment. A title company is essential to ensure the deed is recorded correctly and the title is clear of liens, providing legal certainty for both the buyer and the lender.
Who chooses the title company in Indiana?
Typically, the party paying for the Owner’s Title Insurance policy has the right to choose the title provider. While this is often a point of negotiation within the purchase agreement, it usually follows local county customs regarding which party covers specific closing costs.
How long does a real estate title search take in Indiana?
A standard title search is typically completed within 3 to 5 business days. However, the timeline can vary depending on the complexity of the property’s history, the county in which the records are held, and the presence of any unique legal "clouds" on the title that require further investigation.
So, you’re buying a new home.
Whether you’re a first-time homebuyer or not, there is a lot to be excited about, but a mortgage is probably not one of them. While helpful, it is challenging to take a loan this size. Therefore, before signing any contract, be sure to understand what a mortgage is.
In this post, we’ll cover the two common types of loans borrowers use to buy their homes — jumbo and conventional loans.
We’ll dive into their differences, their own advantages and disadvantages, and more to know which one is right for you, so without further ado, let’s get started.
Jumbo loans, sometimes referred to as jumbo mortgages, are large loans that exceed the borrowing limits set by the Federal Housing Finance Agency (FHFA).
Mortgages falling within the annual lending limits imposed by the FHFA are referred to as conforming loans. Conforming loans can be bought by two government-sponsored entities, Fannie Mae and Freddie Mac, which frees up cash for lenders. Loans over that amount, however, are considered non-conforming loans and carry greater risk for the lender because they are not insured or guaranteed.
Homes that cost more than the FHFA loan limit can be paid for with the aid of jumbo loans. Buyers are usually well-off individuals who want to buy a luxury residence of some kind.
Conventional loans, also known as conventional mortgages, are a common category of loans that are not covered by government insurance directly.
However, as previously noted, the majority of conventional loans are conforming, which means they fall inside the FHFA credit restrictions and may be purchased by Freddie Mac and Fannie Mae.
Since their mortgage does not violate FHFA loan limits, buyers are usually low-to-moderate income earners who are looking for more conventional housing.
Now that you know the basics of jumbo and conventional loans, it’s time to learn about their key differences.
Requirements
More or less, the kind of loan you take out will be greatly influenced by your financial condition; therefore, look over the typical funding requirements to assist you in making a decision first. However, bear in mind that when you apply for a loan, a lot of things could affect your eligibility. If this is your first time purchasing a home, this covers your salary as well as the intended home's size, among other factors. You may see a good range of qualifications in the following table.
| Requirements | Jumbo Loan | Conventional Loans |
|---|---|---|
| Maximum Amount of Loan | Multiple Million Dollars | $766,550–$1,149,825 (location-specific) |
| Credit Rating | 680 + | 620 |
| Down Payment | 20% | 3%-20% |
| Reserves Required | Up to 12 Months | Up to 6 Months |
| Maximum Debt-To-Income Ratio (DTI) | 45% | 50% |
| LTV Ratio | Less or Equal to 89.99% | Less or equal to 97% |
Pros & Cons
Let's now list a few advantages and disadvantages of jumbo vs. conventional loans.
Jumbo Loans
Pros
Cons
Pros
Cons
In some situations, jumbo loans make more sense than conventional loans.
What do you want to purchase?
How do things stand financially for you?
What is your credit score?
Let's understand these situations.
High-end housing is a common usage for jumbo loans. This could be a vacation home, a luxury property, or just a house in a posh neighborhood. Individuals who apply for jumbo loans usually have excellent credit and are well-off.
Conventional loans are utilized for mortgages up to the FHFA loan limit and are usually conforming loans. It is the far more typical kind of loan. The majority of buyers have modest to moderate incomes and good credit.
Find Your Best Option With The Experts At IndyLegal
We can't wait for you to purchase your new home! We commend you for taking the time to learn more about financing your home, even though we understand that money is probably the last thing you want to think about. Don’t worry, our experts here at IndyLegal are happy to help so you can find the best mortgage option for you. Talk to us to learn more by leaving a comment or clicking this link.
In the highly competitive markets, time is of the essence for both real estate professionals and prospective purchasers. One of the most annoying obstacles for all parties involved when balancing timeframes and transactions is a delayed close.
For real estate professionals, such as brokers, realtors, or lawyers, anticipating and resolving possible obstacles is often essential to handling the intricacies of a transaction.
Your title company partner is crucial to ensuring a smooth closing process and guaranteeing that your clients have an unforgettable experience. Let's discuss how clients benefit from the title clearance process, which serves as a crucial safeguard in the marketplace.
Understanding your deadlines and milestones is the first step in controlling the closing timeline. In the dynamic real estate market of today, delays might have detrimental effects:
It's a delicate dance to maximise efficiency while striking a balance between corporate expansion and customer service. Utilizing the latest technologies will help you ensure that you meet your objectives and achieve successful results. Having a skilled title insurance officer on your staff provides your clients with important protection, especially as real estate scams and cybercrime increase and more consumers desire the convenience of remote closings.
It's possible that some customers, particularly first-time buyers, are unaware of the need for title insurance to protect their investment against flaws in the property's title. Liens, encumbrances, and claims from unidentified heirs or other third parties are examples of these clouds that may cause a significant loss of value. One of the most frequent reasons for closing delays is unresolved title concerns, including liens or ownership disputes. Before the title is transferred, any outstanding debts associated with the property must be paid off.
The power of early detection in title insurance helps realtors stay on track. Title searches reveal potential difficulties that could complicate the transaction. Before closing, this is done to give all parties sufficient time to resolve any outstanding issues. A trustworthy title insurance company detects and resolves concerns early. Another important service title insurance provides is lien clearance. Title experts can help resolve mechanics' and tax liens that could delay closing.
Title experts resolve these difficulties quickly to ensure a smooth closure. Title insurance professionals assist brokers, lenders, and attorneys by providing property documents and updates. Title officers can coordinate title commitments, closing numbers, and escrow accounts, giving you and your clients peace of mind. These collaborations keep transactions on track and avoid final shocks.
Real estate professionals using a full-service title insurance and escrow provider experience fewer delays because title review, document signing, and wire transfers are all handled in one place. This reduces confusion and delays caused by many people working on separate stages of the process.
Our expertise at IndyLegal Title Services enables us to tailor our offerings for virtually any type of property, including commercial, residential, and agricultural land. Title insurance professionals who grasp these subtleties and adjust their services benefit realtors, brokers, attorneys, and their clients.
Closing delays are unpredictable, but your title insurance partner reduces the risks. Contact us today to enhance client connections and expedite closings!